Caesars Details Why It Chose Fertitta Deal Despite Higher Icahn Offer
Carl Icahn put $34 per share on the table. However, Caesars ultimately stuck with Tilman Fertitta’s $31 offer after months of competing takeover talks.
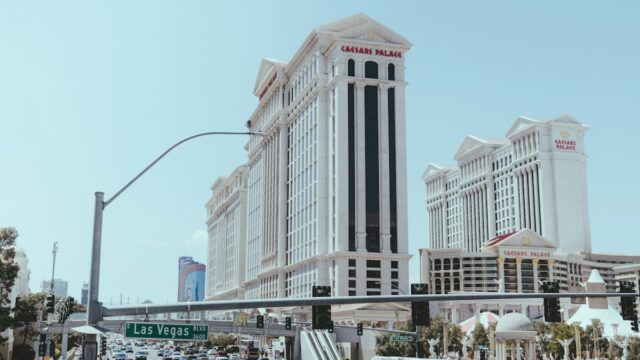
A new proxy filing has shed light on Caesars Entertainment’s proposed acquisition by Tilman Fertitta and why the company chose that offer over a last-minute higher bid from Carl Icahn, revealing concerns over financing, leverage and the structure of the rival proposal.
The preliminary proxy statement, filed with the Securities and Exchange Commission (SEC) on Aug. 12, provides a detailed chronology of negotiations leading to the $17.6 billion Fertitta transaction and Icahn’s subsequent effort to challenge the deal.
The disclosure shows the two sides had competed for Caesars since January, a month before news surfaced on Fertitta’s potential offer. Icahn initially offered $28.50 per share, while Fertitta entered at $28.75 before both sides progressively raised their bids.
In early February, Icahn reached $32 per share, with Fertitta matching the offer days later. Icahn later indicated that he would no longer move forward, although he returned later that month with a $33-per-share proposal.
Fertitta then reduced his offer to $31 amid higher financing costs and increased macroeconomic risks. Caesars initially rejected the reduced offer and countered with $31.50, then $31.25. Fertitta refused to increase his offer before the companies ultimately agreed to the $31-per-share transaction in May.
The acquisition remains pending regulatory and shareholder approvals. Caesars released its latest quarterly results without an earnings call because of the pending transaction.
Icahn Returned With $34 Caesars Offer
The Fertitta acquisition included a 45-day “go-shop” period until July 11. During that period, Caesars could solicit and negotiate alternative acquisition proposals.
In early July, reports emerged that Icahn was considering an eleventh-hour bid. The new filing now confirms that Icahn submitted a non-binding $34-per-share cash proposal on July 10. The offer was higher than his previous bid and Fertitta’s agreed price.
The proposal contemplated approximately $1.4 billion in cash, around $860 million in rollover equity and $6.5 billion in new debt financing from Jefferies. It also assumed that at least five million shares held by the Carano family would be contributed to the buyer’s vehicle.
Although the formal go-shop period expired the following day, Fertitta’s acquisition vehicle agreed to extend Caesars’ deadline twice to determine whether Icahn qualified for continued special treatment under the merger agreement. Caesars was ultimately given until Aug. 10 to evaluate the rival proposal.
Caesars Raised Concerns Over Icahn Financing
There were questions about the certainty of Icahn’s financing.
First, with respect to the July 10 offer, Jefferies’ draft debt commitment was unsigned, undated and incomplete. Jefferies later told Caesars’ advisers that it could not execute the transaction without commitments from other, not-yet-identified investors.
Caesars identified several economic issues with the Icahn offer. Those included high leverage, lack of liquidity and the possibility that most of the resulting company’s free cash flow would be required to service interest on its new debt.
According to the filing, Caesars believed those issues posed execution risk because gaming regulators focus heavily on licensees’ financial profiles.
The proposed structure also relied on the Carano family rolling equity into the new company. On July 14, Caesars Executive Chairman Gary Carano and CEO Tom Reeg told Icahn representatives that the proposed rollover equity was less attractive than under the Fertitta transaction. Also, the Carano family said it would not participate under the terms then proposed.
Icahn attempted to address the concerns by proposing to eliminate $1 billion of debt and replace it with additional equity. Caesars continued to question where that equity would come from, how additional financing would be raised, and Icahn’s proposed reductions in capital expenditure.
Caesars’ board, meanwhile, identified Fertitta’s ability to avoid triggering change-of-control provisions in existing debt as a benefit of his transaction. The structure allows substantially all existing Caesars’ debt to be rolled over. That would reduce new financing requirements and, according to the board, improve deal certainty.
Discussions continued into August, but Caesars said on Aug. 10 that there had been “no material progress on the fundamental issues” it had raised. Icahn’s extended window then expired, limiting Caesars’ ability to continue discussions under the merger agreement.


Gambling Insider delivers the latest industry news, in-depth features, and operator reviews that you can trust. Our team combines rigorous editorial standards with decades of specialized expertise to ensure accuracy and fairness. We are committed to delivering clear, impartial, and dependable coverage across the global gambling sector.